Money in the First Six Months of a Small Business: What I Learned on the Ground in Pune
Nobody loses their business on opening day. Opening day is the easy part. There are flowers, there are photos for WhatsApp status, there is a cousin who buys the first item and pays double. The business is decided later, in six quiet months that nobody films, when the rent date keeps coming back and the customers do not.
I have watched this happen to too many founders to stay quiet about it. Money in the first six months of a small business follows a pattern. Kirana shop, tiffin kitchen or two-person studio, same pattern. If you know the pattern before you start, you plan for it and you survive. If you meet it for the first time in month three, it meets you at the worst possible moment.
What I cover in this one
Why Money in the First Six Months of a Small Business Breaks Every Budget
Most first-time founders never write a real budget. Not because they are careless. A real budget needs answers that a new founder simply does not have yet: how long the first customers will take to find you, what a licence really costs once every fee and form is counted, how a supplier’s payment terms work in real life. So the founder keeps a rough number in their head and starts.
I am writing this part sitting on the cool stone floor of a small Lord Shiva temple near Marunji, in Nere Dattawadi village, a little outside Hinjewadi. I have been in Maharashtra for a while now, and I will be here for the next few weeks, so forgive me if Pune keeps entering this article. It earned its place.
Here is the trouble with that rough number. It is built only from costs you can picture. The costs that hurt are the ones nobody pictured: the second trip to fix the first installation, the deposit nobody mentioned, the slow fortnight that was supposed to be busy. Startup cost reality for small businesses almost always sits above the first estimate, and in my experience the gap comes from these unlisted items far more often than from one big extravagant purchase.
The second problem goes deeper. Income and expenses run on different clocks. Rent comes on the first. Salaries go out on the seventh. The loan instalment hits on the fifteenth. Income comes whenever customers decide to buy, and in a new business that is slower and more irregular than you hoped. Cash flow for a new small business is shaped by this mismatch. A founder can have a good business and still run out of cash, simply because the bills keep their schedule and the customers do not.
Where Small Business Money Actually Goes, Month by Month
Following the money month by month shows you the pattern far better than any one total.
Month One: Where Small Business Money Actually Goes First
Registration and licence fees, the first stock or equipment, a deposit and the first rent if you have a premises, signage, and a surprising number of small fixes as your plan meets reality. Revenue this month is usually small enough to ignore when you plan.
Months Two and Three: The Gap That Squeezes Cash Flow for a New Small Business
Setup is mostly paid. Now the running costs start: rent, electricity, supplies, any staff, marketing to find customers. Revenue grows, but slowly, because word of mouth takes time. This is where the distance between money going out and money coming in is widest. New business cash flow planning has to be built around this stretch, and it is exactly the stretch most rough budgets ignore.
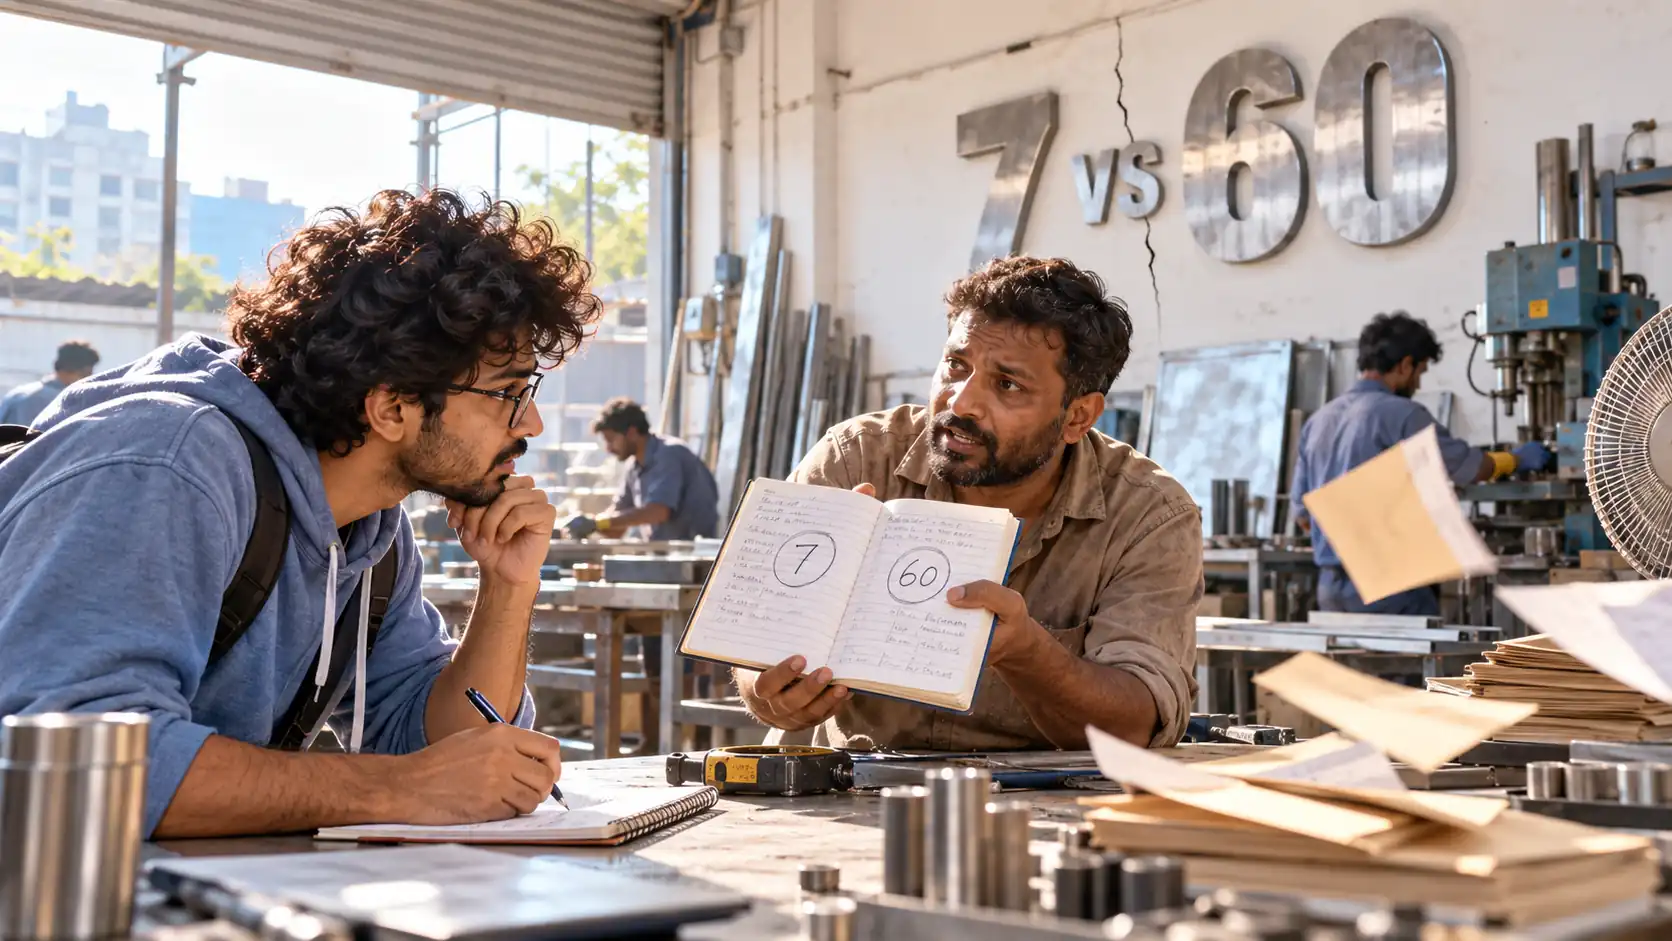
I saw this gap with my own eyes this week. I have been taking autos all over Pimpri-Chinchwad and Hinjewadi Phase 1, 2 and 3, meeting small business owners and asking them one simple question: walk me through your day. A small fabrication unit owner in Pimpri-Chinchwad showed me his notebook. His workers get paid on the seventh, without fail, because they have families. His biggest customer pays in sixty days, sometimes ninety. He is not short of work. He is short of time between those two dates. That is the gap, sitting right there in blue ink.
Months Four to Six: The Turn in First Six Months Business Expenses
In a business that is working, revenue climbs to meet the monthly costs somewhere in this window. The gap narrows a little every month, and the founder finally understands the real rhythm: which days are busy, which products move, which customers come back.
| Expense | When it hits | What founders usually underestimate |
|---|---|---|
| Registration and licences | Month one | Fees and documents discovered halfway through |
| Stock or equipment | Month one, then again soon after | A second purchase to correct the first |
| Rent and utilities | Every month, fixed dates | How little room there is in a slow month |
| Marketing to find customers | Months one to three | How long it takes to show results |
| Working capital reserve | Should exist from day one | Underfunded, or skipped completely |
A ₹2 Lakh Sketch: Cash Flow for a New Small Business in Real Numbers
Let me give you numbers, because numbers are where the truth hides. Picture a woman starting a small home food business with ₹2,00,000 saved. She keeps ₹40,000 for setup: kitchen equipment, FSSAI registration, packaging and her first ingredients. The other ₹1,60,000 she keeps as a reserve and promises herself not to touch.
- Month one uses the full setup budget plus ₹35,000 from the reserve for early ingredients and the small mistakes every new kitchen makes. Reserve: ₹1,25,000.
- Months two and three pull out ₹60,000 more. Orders grow, but they still do not cover the full monthly cost. Reserve at its lowest: ₹65,000.
- Month four is the first month revenue covers the month’s costs.
- Months five and six add a little back. Reserve by the end of month six: around ₹75,000.
Now run the same story without the reserve. With only the setup money, she runs out in month one, long before the business ever had a chance to work. The reserve is what carries her across the gap to month four. That is its only job. These are illustrative numbers and yours will change with your city, your prices and your trade. The shape, a deep dip in months two and three and a slow climb back, is what repeats.
Pune has been good to me on the food side, I will admit it. Misal that makes your eyes water, vada pav at odd hours between meetings, poha at a small stall near Hinjewadi Phase 1 at seven in the morning. The man running that stall told me he buys his potatoes and onions every morning in cash and gets paid in coins and UPI through the day. By noon he knows if the day made money. Most bigger businesses only know that at month end.
Startup Cost Reality for Small Businesses Changes With the Type of Business
The dip shows up almost everywhere. How deep and how long depends on what you build.
| Business type | Where the money goes first | What the dip looks like |
|---|---|---|
| Service built on your own skill (tutoring, design, repairs, consulting) | Tools, a phone, your own living costs | Shallow, but depends on how fast clients come through referrals |
| Retail with stock | Inventory, before a single sale | Deep if the first order was too big or the wrong mix; cash sits on shelves |
| Food or small production | Equipment, licences, raw materials bought ahead | Moderate but long, because reputation spreads slowly |
| Selling to other businesses | Delivery costs while you wait to be paid | Big early orders, then weeks or months before the money lands |
That last row is the one that surprises people the most. If you sell to other businesses, a signed order is not revenue. Money in the account is revenue. Startup cash flow in India has to be planned on that basis, because large buyers here often pay on credit terms that stretch for weeks.
- How to Check if Image Is AI Generated: A Five-Step Routine for Indian Users
- n8n Webhook Not Working? The Real Reasons and the Fix for Each

- AI Agents Market Saturation 2026: Which AI Agents Are Actually Useful (And Which Are Just Noise)
- Claude Code Beginner’s Guide 2026: Login, Commands, Cheat Sheet & Honest Comparison
Two Founders, Same Idea: Small Business Money Mistakes Early On
Picture two founders opening similar small shops in the same city in the same month, with almost the same savings.
The first one splits her money with discipline: setup, a careful first stock order, and a protected reserve. When sales grow slowly in months two and three, the reserve absorbs it. By month five her sales cover her costs.
The second one spends more on day one: a bigger first order, a nicer interior, because a fuller and smarter shop should bring customers faster. Customers arrive at roughly the same speed as at the first shop. With no reserve, he spends month three looking for an emergency loan to pay rent, and the only lender ready to move fast charges a painful rate.
Same idea, same market, same starting money. The only difference was the order in which the money was spent. That one choice decided who spent month six planning and who spent it running. When people ask me where small business money goes wrong, this is my answer nine times out of ten: too much of it was committed on day one.
The Working Capital Reserve: Hidden Inside First Six Months Business Expenses
If I could change one habit in every first-time founder, it would be this: fund the working capital reserve properly before you spend on anything that can wait.
The reserve covers the gap between spending and earning. It pays the rent in a slow month, buys the second batch of stock when the first sells faster than expected, and lets you say no to a desperate, expensive loan. Among the founders I have worked with, an underfunded reserve has ended more good businesses than any other single reason.
It gets underfunded because it is invisible. Setup money buys things you can photograph. A reserve just sits in an account looking lazy, so founders spend a little on a better board or a bigger order and reach month two with far less cushion than planned.
I understand this one personally right now. I came to Pune for one client meeting, and honestly it is a very big opportunity for me. But I am alone on this trip. My wife decided to stay back home and skipped this one, so it is just me and one bag, booking my own autos, finding my own food, and in between handling every automation build, every client call and every free service request myself. My reserve on this trip is not money. It is time and energy, and I am learning to protect it the same way I tell founders to protect their cash.
Small Business Budgeting for Beginners: How to Size the Reserve
- List your fixed monthly costs. Rent, electricity, salaries, loan instalments, subscriptions, anything that comes whether you sell or not. Add a small amount for supplies you will need regardless.
- Estimate honestly when revenue will cover those costs. Then assume it will take longer. In almost every business I have sat with, the ramp was slower than the founder’s first guess.
- Size the reserve to cover fixed costs for every month until that later break-even point, plus a margin for surprises. If that number is huge, that is useful information. It may mean starting smaller, or saving a little longer.
Keep it in a separate account from both your personal money and your daily business account, reachable within a day, and out of shares or long lock-in deposits. Its job is to be there in month three at full value, not to grow.
A First-Month Budget for Small Business Budgeting for Beginners
If you have never written a budget, fill in this list before you spend a single rupee. Your first six months business expenses will mostly fall into these lines.
| Type | Lines to fill in |
|---|---|
| One-time costs | Registration and licences, any help with paperwork, equipment and tools, first stock or raw materials, premises deposit, interiors and board, launch marketing and photos |
| Monthly costs | Rent and electricity, salaries or helpers, stock to replace what sells, phone, internet and software, transport and delivery, loan instalments, marketing to keep finding customers |
| The reserve | Fixed monthly costs multiplied by the months until a cautious break-even, plus a margin for surprises |
Fill every line, even roughly. A blank line is usually a cost you will meet unprepared.
Tracking Money in the First Six Months of a Small Business, Week by Week
Four numbers, checked every week on the same day, are enough to know where you stand inside the pattern.
| Number | Why it matters |
|---|---|
| Reserve balance | A falling number noticed early is manageable. Noticed late, it is a crisis. |
| Revenue against your cautious estimate | Compare with the careful estimate, not the hopeful one you started with. |
| Monthly gap | Revenue minus fixed costs so far this month. Shows how fast the reserve is used or rebuilt. |
| Surprises | Every cost that came in higher than planned, with the reason. In six months this becomes your most honest budget. |
This is where I want to be honest about why I am really here on the ground. I have built many automations for small businesses from my laptop. But a workflow built from a laptop only knows what the owner remembered to tell me. So this trip I am meeting authors, automation engineers and shop owners face to face, to see the real gaps between what owners struggle with every day and what tools actually reach them. Almost every owner I met keeps these four numbers somewhere: a notebook, a calendar, a WhatsApp chat with himself. Almost nobody looks at them every week.
You do not need fancy software for this. A simple Google Sheet works. If you use an AI assistant like ChatGPT or Claude, paste your week’s figures in every Sunday and ask it three questions: is my gap narrowing, which cost grew the most, and how many weeks does my reserve last at this rate. It takes five minutes and it never gets tired of looking at bad numbers, which is exactly when humans stop looking.
Three Checkpoints for New Business Cash Flow Planning
Besides the weekly numbers, stop at three points and answer a few questions on paper. Memory softens bad months and inflates good ones. A page written at the time does not lie.
| Checkpoint | Questions to answer honestly |
|---|---|
| End of month one | Did setup cost more than planned, and by how much? Which costs were missing from the budget? Did setup eat into the reserve? If yes, refill it or shrink your plans now. |
| End of month three | Is the monthly gap narrowing, even a little? What brings most of the money? Which customers came back? If you had to cut one cost tomorrow, which one? |
| End of month six | Does revenue cover monthly costs? If not, how far away is that point and does the reserve last that long? What did you learn about pricing and your customers? |
Small confession in the middle of all this money talk: I love travelling, and this Maharashtra trip has reminded me how much. If you want me to write my personal travel blogs too, tell me in the comments, bro. If this article gets 10 comments, I will open a Travel category on Ethical Founder and start writing my travel history there. Positive or negative, both count. So far I have never received a negative comment here, so if you want to be the first, go ahead.
Warning Signs and Small Business Money Mistakes Early On
- The reserve falls faster than planned two months in a row. One bad month happens to everyone. Two in a row is a pattern. Cut a cost or fix an assumption now, while there is cash to work with.
- Revenue and profit get mixed up. A month with strong sales can still lose money once every cost is counted. Track profit roughly from month one.
- Borrowing to pay routine costs. A loan for planned equipment is a business decision. A loan for this month’s rent, especially from an informal lender at a high rate, is a warning sign.
- Avoiding the numbers. When the reserve falls, looking at it hurts, so many founders stop looking. This is the most human mistake and the most expensive one.
- Personal and business money in one account. You can no longer see the business’s real position. Open a separate account in month one.
- Underpricing to win the first customers. Customers who joined at a low price resist increases, so you stay stuck with thin margins.
Getting Paid Faster: Startup Cash Flow India Habits That Work
Money owed but not yet received causes much of the pressure. Faster collection eases the gap as much as cost cutting.
- Take advances where your trade allows. Custom orders, catering, tailoring and event work can ask for a deposit before starting.
- Collect at the moment of delivery. A UPI QR code at the counter or a payment link sent with the order makes paying instant,.
- Be careful with credit. Every rupee given on credit is a rupee missing while your own bills keep coming. Write clear terms and follow up politely on the due date, every time.
In Hinjewadi Phase 3 I met a young couple running a laundry and ironing service for the IT crowd. Their problem was not customers. They had plenty. Their problem was monthly billing: they washed for thirty days and collected on day thirty-five, while the detergent, the electricity and the delivery boy’s salary were all paid upfront. We sat on a bench outside a chai shop and sketched a simple automated reminder that sends a UPI link the moment an order is delivered. Small thing, big relief. This is exactly the kind of gap I came here to find.
When the Reserve Runs Low: Small Business Financial Survival in the First Year
Sometimes the reserve shrinks faster than planned even with good habits. If it happens, act in this order.
- Talk to the people you owe before you miss a payment. A landlord, supplier or bank told early about a short-term problem will often adjust a date. One told after a missed payment has far less goodwill.
- Cut costs that do not bring revenue. Subscriptions and non-essential spending first. Be slow to cut the marketing and stock that bring sales.
- Collect what you are owed. Firmly and politely. A small discount for quick payment can bring money in sooner.
- If you must borrow, borrow formally. A working capital loan from a bank on small-enterprise terms costs far less than informal credit and comes with a repayment plan you can work around.
- Revisit the plan. A low reserve is information. Prices may be too low, costs too high, or the business may need to start smaller.
When It Is the Model, Not the Money in the First Six Months of a Small Business
Most businesses that struggle in these months are just slow, and slow can be survived with a reserve and patience. A smaller number have a deeper problem: the business, as designed, loses money on every sale, or cannot find enough customers at a price that covers its costs.
The signs: customers try once and rarely return, each sale fully costed earns less than it costs to deliver, and revenue has stopped growing for two or three months while costs stay put. If you see these, more reserve only delays the end. Change the price, the product or the customer. Call the people who left and ask why. Sometimes the honest answer is to close while savings can still fund your next attempt. Reaching that at month six with money left beats reaching it at month eighteen with nothing.
What a Family Safety Net Does to Startup Cost Reality for Small Businesses
One thing shapes these months for many Indian founders and almost never appears in business advice: whether family money stands quietly behind the business as an unofficial reserve.
A founder who knows a parent or sibling could step in during an emergency feels months two and three very differently. Nothing wrong with that support. Just be honest about whether it exists and how far it stretches, because it changes how much risk you can take.
For a founder without that backstop, the official reserve is the whole margin for error. Size it more carefully than feels necessary, start smaller, and take the first warning sign seriously. Your plan for small business financial survival in the first year should be built for the case where nobody can rescue you, because for you that is the real case.
Family is on my mind as I write this, sitting here alone in this Shiva temple. My wife is at home, I am here with one bag and a laptop full of client work. Before I leave this temple today, I am going to sit for a few minutes and pray. For my client meeting, yes. But mostly for every one of you reading this who is somewhere inside month two or month three right now, looking at a number that scares you.
Where Udyam, GST and Formal Credit Fit Into Startup Cash Flow India
Some of your first six months business expenses are paperwork that pays for itself, and doing it early makes the cash picture easier.
- Udyam registration is free and fully online. The official portal itself says no fee is to be paid to anyone, so ignore agents who charge for it. It gives your business a formal MSME identity, which is the starting point for MSME lending schemes.
- CGTMSE provides guarantee cover so banks and other member lenders can give collateral-free credit to micro and small enterprises. If you do need working capital to cross the gap, a registered business can approach a bank, or SIDBI and its partner lenders, on far better terms than an informal lender.
- GST registration becomes mandatory once your turnover crosses the threshold for your business and state, and some founders register earlier because their customers need GST invoices. Check the current rules on the GST portal.
- NSIC runs a Raw Material Assistance Scheme that finances purchases of raw materials for MSMEs.
- Startup India recognition may help founders building something new as a company or LLP. Check the criteria first.
Tomorrow evening I leave for Lonavala. No client work there, I promise. Just a weekend for myself, some hills, some rain if I am lucky, and then back on the road on Sunday night or early Monday morning to continue meeting people. If any of you run a small business between Pune and Lonavala and want to show me how your day works, write to me. I am on the ground for a reason.
Borrow for the Gap or Save Longer? New Business Cash Flow Planning Decides
When the reserve your budget needs is bigger than the money you have, you face a choice: borrow the difference, or wait until your savings catch up. Both can be right. The deciding question is how predictable your business is.
| Your situation | Usually wiser | Why |
|---|---|---|
| Tested model: a skill you have already sold, or orders already lined up | A modest formal loan sized to the gap | Repayments become a fixed cost your cautious revenue estimate can carry |
| Untested idea | Save longer, or start small as a side project | A loan adds a fixed repayment to the most uncertain months, and you lose the freedom to change the idea |
And build your estimate around India’s own rhythm, not a foreign template. Festival seasons bring a surge of sales, and a surge of stock purchases before them. Monsoon months slow footfall in some trades. Bigger buyers pay on credit that stretches for weeks. Build the reserve before the shopfront. If you are already in month two or three and the numbers frighten you, open them anyway this week, write down what you see, and make one decision based on it.
Questions Founders Ask About Money in the First Six Months of a Small Business
How much money should I keep aside for the first six months of a small business?
Add up your fixed monthly costs (rent, electricity, salaries, loan instalments, subscriptions), multiply by the number of months until a cautious break-even point, and add a margin for surprises. Keep this reserve separate from your setup budget and do not spend it on improvements.
Why do small businesses run out of cash even when sales are growing?
Because expenses arrive on fixed dates while income arrives whenever customers buy. In months two and three the gap between the two is usually at its widest, so a growing business can still run short of cash if it has no reserve.
Is Udyam registration really free?
Yes. The official Udyam registration portal says the process is totally free and no fee is to be paid to anyone. Avoid agents who charge for it.
Should I take a loan to cover the first six months of a new business?
Only if your model is already tested, for example a skill you have sold or orders already lined up, and only a formal loan sized to what your cautious revenue can repay. For an untested idea, saving longer or starting smaller is usually wiser.
What should I track every week in the first six months of a small business?
Four numbers: your reserve balance, revenue against your cautious estimate, the monthly gap between revenue and fixed costs, and every cost that came in higher than planned.